Innovation, when the market itself is the product.
In a mature retail economy, innovation means a better app or a faster checkout. In a market where organised retail barely exists, it means building the category. This page examines the difference — and what it demands of an operator.
The context
Moroccan retail is still, predominantly, traditional.
This is the single most important fact for understanding why the group was built the way it was — and it remains true today.
~69%
of total food retail sales in Morocco are made through small local grocers, according to 2024–25 sector reporting — a market still dominated by traditional outlets.
of active Moroccan businesses are led by women, with the highest concentrations in Marrakech-Safi, Casablanca-Settat and Rabat-Salé-Kénitra.
OMTPME, October 2022
19%
female labour-force participation in 2024, down from 28% in 2000 — leaving one of the widest recorded gender gaps in the world.
World Bank
Casablanca
A market of that shape is not waiting for a better version of organised retail. It is waiting for organised retail at all. That changes what counts as innovation in a fundamental way: the difficult, valuable work is not differentiating within a category but establishing one — assembling supply chains, standards, physical space, trained staff and consumer trust more or less simultaneously, and doing it profitably enough to fund the next stage.
It also changes the risk profile. An entrant to a mature market inherits infrastructure and competes on execution. An entrant to an underdeveloped one has to fund the infrastructure out of its own operating margin before it can compete on anything. The failure mode is not being outcompeted; it is running out of capital or credibility partway through building the foundation.
Six innovations
What was actually new.
01 — Formalisation
Turning informal demand into a formal sector
Before 2004, Moroccan demand for international fashion was met largely through travel and unstructured import channels. The Inditex agreement of 2001 and the first African Zara flagship in 2004 moved that demand into a formal retail economy — taxed, regulated, employment-generating, and subject to consumer-protection norms. The innovation was structural rather than technological, and its effects are the most durable of anything on this page.
02 — Destination
Commercial property as a footfall product
Morocco Mall, opened in December 2011, was not designed as a collection of shops. Aquadream — a one-million-litre aquarium with over forty species and a cylindrical viewing tank — and an Atlantic seafront setting were footfall drivers independent of retail demand. That logic, retail anchored by non-retail attraction, is now standard practice internationally; in North Africa in 2011 it was not.
03 — Human capital
Vocational training as competitive infrastructure
AKSAL Academy, founded in 2011, treated a labour-market shortage as an engineering problem rather than a hiring problem. Programmes in retail, services and mall management created the competencies that international franchise contracts require. Few retail groups anywhere operate a training institution of this kind; it is a response to a specific market failure.
04 — Channel
Omni-channel before the market demanded it
AKSAL Digital was established in 2016, in a market where e-commerce penetration was still modest. Building digital capability early, in a group whose largest asset is physical, is a decision that trades short-term cannibalisation for long-term relevance.
05 — Format
The smart store
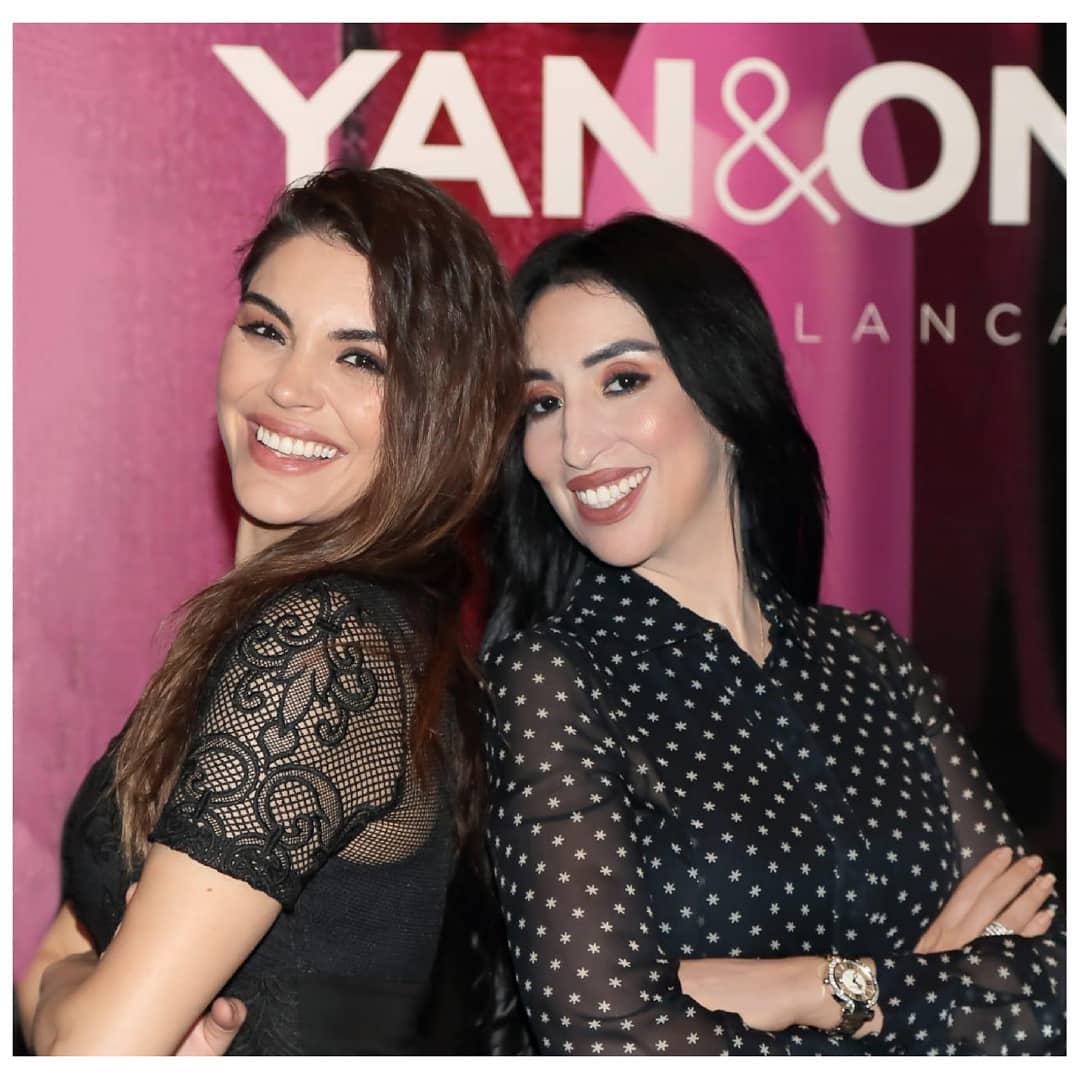
Yan&One, launched in 2017 with a flagship in Morocco Mall, uses digital screens in place of conventional shelf merchandising. Beyond the interface, the significance is data: a screen-led store observes consideration and comparison behaviour that physical shelving cannot, closing part of the information gap between online and offline retail.
06 — Ownership
From franchisee to brand owner
Creating Yan&One changed the group’s economics as well as its capabilities. A franchisee earns a margin on someone else’s intellectual property and inherits its product roadmap. An owner keeps the margin, controls the roadmap, and carries the consumer risk directly. After two decades of representation, the group took that risk.
Beauty retail — AKSAL Cosmetics
Yan&One brand event, Casablanca
Analysis
Why beauty was the right category to own.
Of all the sectors the group could have entered as a brand owner in 2017, cosmetics was the most defensible choice — for reasons that are structural rather than aesthetic.
Lower capital intensity than fashion
Launching a fashion label requires seasonal design cycles, complex sizing and fit, high inventory risk and rapid obsolescence. Cosmetics carries longer product lifecycles, simpler SKU management and far lower markdown exposure. For a first move into brand ownership, it is materially less dangerous.
Existing distribution and category knowledge
AKSAL Cosmetics already operated in beauty, including Sephora in Morocco. The group therefore entered brand ownership with category expertise, supplier relationships and shelf access already in hand — a very different proposition from starting cold.
A category where local relevance is an advantage
Beauty preferences vary meaningfully by climate, skin tone and cultural practice. Global brands necessarily generalise. A regionally rooted brand can address specifics that international ranges treat as edge cases — which is precisely where a domestic entrant has an advantage a multinational cannot easily replicate.
Compatibility with the smart-store format
Beauty is a high-consideration, high-comparison purchase in which customers actively want information: ingredients, shades, application, comparisons. A screen-led store is genuinely more useful in that context than in categories where shoppers already know what they want. The format and the category reinforce each other.
Outlook
The next constraint.
Every stage of this group’s history has been defined by the binding constraint of its moment. The current one is format.
The large-format shopping centre is under structural pressure worldwide. Online retail has taken the transactional function that malls were originally built to serve, and the destinations that continue to perform are those offering something a screen cannot: food, culture, leisure, social space, the experience of being somewhere.
The group’s recent moves read as a direct response. AKSAL Developments has announced smart lifestyle and social-shopping projects for Marrakech, Rabat and Bouskoura — formats that blend commerce with leisure and public space. AKS Mode, registered in Casablanca on 31 July 2023, extends the group into hospitality, catering and fast food, disciplines that supply exactly the non-retail reasons to visit that modern destinations depend on.
The geographic choice is also notable. Marrakech, Rabat and Bouskoura are three quite different propositions: an international tourism economy, an administrative capital, and a fast-growing satellite of Greater Casablanca. Testing a new format across three distinct demand profiles is a more informative strategy than replicating one model three times.
Whether the response proves sufficient is genuinely open. Retail formats have been disrupted before, and operators with strong physical assets have historically been slower to adapt than their statements suggest. What can be observed is that the group identified the constraint early, and has committed capital against it rather than defending the existing model — which is the same pattern visible at every previous stage of its history.
What generalises from this case
The transferable lesson is not “build a mall” or “start a training academy”. It is a method: identify the constraint that will eventually cap everything else, and address that in preference to the growth immediately available. In an underdeveloped market, the constraint is almost never demand. It is infrastructure, standards or skills — and those take years, which is precisely why most operators postpone them.