Salwa Idrissi Akhannouch Businesswoman & Entrepreneur Enquiries

Insights

Four questions
this career
answers.

Longer-form analysis on the structural problems behind the story: how brands enter emerging markets, what a shopping centre is actually for, why a retailer would build a school, and what changes when you stop selling other people’s brands.

What it actually takes to bring a global brand into an emerging market

The franchise agreement is the last step, not the first. By the time a signature is possible, the difficult work is already done — which is why so few operators in underdeveloped markets ever reach that point.

The brand’s real question

An international retailer assessing a new market is not primarily asking whether demand exists. Demand is usually visible, often for years, in travel spending, e-commerce leakage and grey-market activity. The question is whether the brand can be operated to its own standard in that market without management attention it cannot spare.

That resolves into a set of specific concerns: can stock be imported and cleared predictably; can stores be built and maintained to specification; can staff be recruited and trained to deliver the service standard; can pricing hold; can the partner report accurately; and can any of this be sustained through a downturn, a currency movement or a regulatory change.

Why operating history is the currency

None of those questions is answered by capital. They are answered by a track record of moving goods through the specific market in question. Espacia, launched in 1994, provided precisely that: a decade of direct exposure to Moroccan import mechanics, clearance, warehousing, pricing and merchant relationships. When the Inditex agreement was concluded in 2001, it rested on operating credibility accumulated over seven years.

The choice of partner also compounds. Inditex runs one of the most execution-dependent models in retail — short design-to-shelf cycles, continuous replenishment, uncompromising store standards. Holding that relationship functions as external certification for every subsequent negotiation, which is why the first African Zara flagship in 2004 mattered well beyond its own revenue.

The sequencing lesson

Operators who try to enter the franchise business directly, without the underlying distribution history, generally fail at the diligence stage. The apprenticeship is not a delay before the real business begins. It is the asset the real business is built on.
The shopping centre as commercial infrastructure

Morocco Mall opened on 1 December 2011 with more than 350 retailers on a ten-hectare Casablanca seafront site, developed at a reported cost of around €175 million. The interesting question is not its size. It is what a destination of that scale does to the commercial geography of a city — and why a retail operator would take on development risk at all.

The constraint that forced the decision

By 2009, AKSAL held franchise rights the Moroccan property market could not properly house. International retailers assess sites on footfall, adjacency, servicing, security, parking, climate control and the calibre of neighbouring tenants. Where no site meets the threshold, an operator faces a permanent ceiling: it can hold the rights but cannot deploy them at the standard the contracts assume.

Developing the site removes the ceiling and, more importantly, transfers control. The group could then guarantee its brand partners the environment they required rather than negotiating for it.

Anchors, attraction and the economics of footfall

A destination of this scale needs traffic that does not depend on any individual tenant. Morocco Mall was let with that logic: Galeries Lafayette secured through agreement with the French group’s president, Philippe Houzé; Fnac; a full complement of luxury mono-brand stores; and Aquadream, a one-million-litre aquarium holding more than forty species, with a cylindrical tank visitors can travel through. Over 5,000 parking spaces made the catchment regional rather than local.

The aquarium is the instructive detail. It generates footfall that is entirely independent of retail demand — families visit for the attraction and shop incidentally. Retail anchored by non-retail attraction is now standard practice internationally; in North Africa in 2011 it was not.

What the industry concluded

The development took Best Shopping Centre at MIPIM in 2012, Best Retail & Leisure Development at MAPIC in 2012, an ICSC Design & Development Gold award in 2012, and Best Retail Development in Africa at the African Property Awards in 2011. It also holds a Guinness World Record for the largest in-store shop facade.

The pressure now

Large-format retail is under structural strain worldwide as transactional demand migrates online. The centres that endure are those offering what a screen cannot — food, culture, leisure, social space. AKSAL Developments’ announced projects in Marrakech, Rabat and Bouskoura, and the 2023 registration of AKS Mode in hospitality and catering, read as a direct response to exactly that shift.

Why a retail group built a school

AKSAL Academy was founded in 2011 — the same year Morocco Mall opened. The coincidence of dates is the whole argument.

The problem a large opening creates

A development with more than 350 stores generates thousands of retail roles more or less simultaneously. In a market where organised retail was barely a decade old, the required competencies did not exist in sufficient supply: visual merchandising, stock and inventory discipline, luxury clienteling, service protocol, loss prevention, centre management. These are learned skills, and nobody in Morocco had been systematically teaching them.

An operator in that position has two options. Accept a standards gap and train informally on the job — cheaper, faster, and corrosive to exactly the franchise relationships the business depends on. Or build the training capacity, at real cost, with a payback measured in years.

Training as quality control

Framed correctly, the Academy is not a social programme. It is quality control applied to the group’s most variable input. If what the group sells its brand partners is the guarantee that standards will hold, then the mechanism producing people capable of holding them is a core operating asset — closer in function to a factory’s calibration process than to corporate philanthropy.

The second-order effect

There is a wider consequence. Retail is one of the few formal sectors offering accessible entry-level employment in urban Morocco, particularly for women, in a labour market where female participation fell from 28 per cent in 2000 to 19 per cent in 2024. A structured training path converts those roles from casual work into a career with recognised competencies and a visible ladder into supervision and management.

That is a more consequential contribution than the demonstration effect of a single successful founder — and it is measurable in a way that inspiration is not.

What changes when you stop selling other people’s brands

In 2017, after more than two decades of representing international labels, the group launched Yan&One — its own beauty and cosmetics brand, with a flagship in Morocco Mall and a store format using digital screens in place of conventional shelf merchandising.

Two different businesses

Franchising and brand ownership look similar from the shop floor and are structurally distinct. A franchisee earns a margin on someone else’s intellectual property, inherits its product roadmap, and carries limited consumer risk — if a range fails, the brand owner absorbs the strategic consequence. An owner keeps the full margin, controls the roadmap, and carries the risk directly. The upside is materially higher and so is the downside.

Why the timing was right

Attempting brand ownership in 2007 would have been premature: the group lacked scale, distribution reach and category depth. Never attempting it would have left the group permanently capped by franchise economics and permanently exposed to decisions taken in Madrid, Paris or Milan.

By 2017 the preconditions were in place. AKSAL Cosmetics already operated in beauty, including Sephora in Morocco, which meant category expertise, supplier relationships and shelf access were in hand. Morocco Mall provided flagship space with guaranteed footfall. AKSAL Digital, established the year before, provided the data and channel infrastructure a new brand needs.

Why beauty rather than fashion

Cosmetics carries longer product lifecycles, simpler SKU management and far lower markdown exposure than apparel — a materially safer first move into ownership. It is also a category where local relevance is a genuine advantage: preferences vary by climate, skin tone and cultural practice, and global ranges necessarily generalise. And it suits a screen-led store, because beauty is a high-consideration purchase in which customers actively want information.

The general principle

Move up the value chain when the capabilities to survive there are already assembled — and choose the category where a first attempt can fail without threatening the business that funded it.

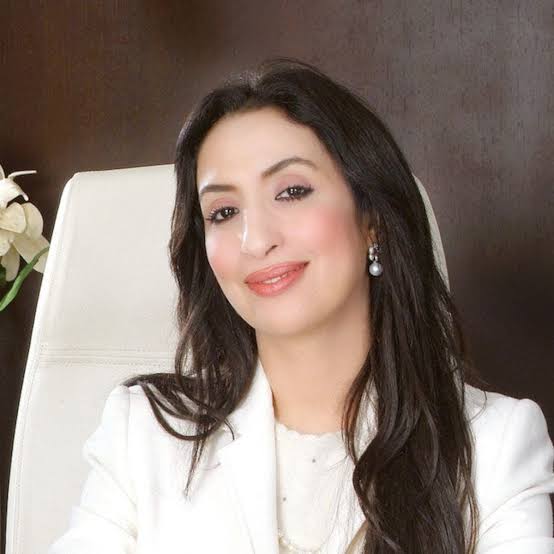
Salwa Idrissi Akhannouch photographed in an office environment.
Casablanca
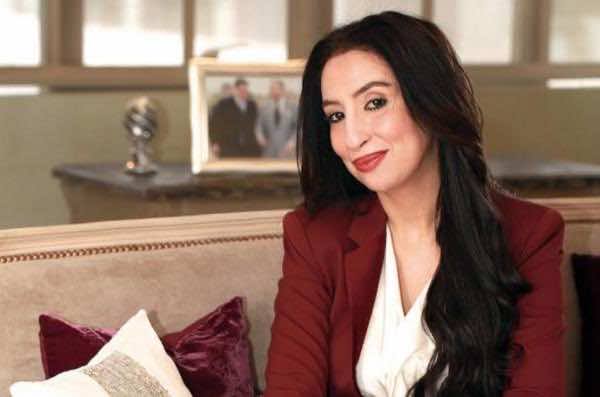
Salwa Idrissi Akhannouch seated in a salon interior.
Portrait
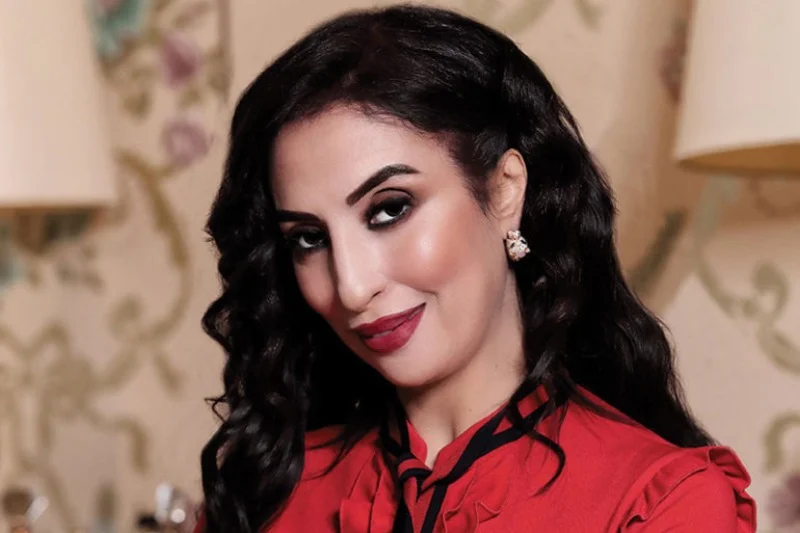
Editorial portrait of Salwa Idrissi Akhannouch.
Editorial portrait

Enquiries

Republication and interview requests.

For permission to quote from these analyses, or for media and speaking enquiries, please use the contact page.